Moving Insurance vs. Valuation Coverage: What Actually Protects Your Stuff?

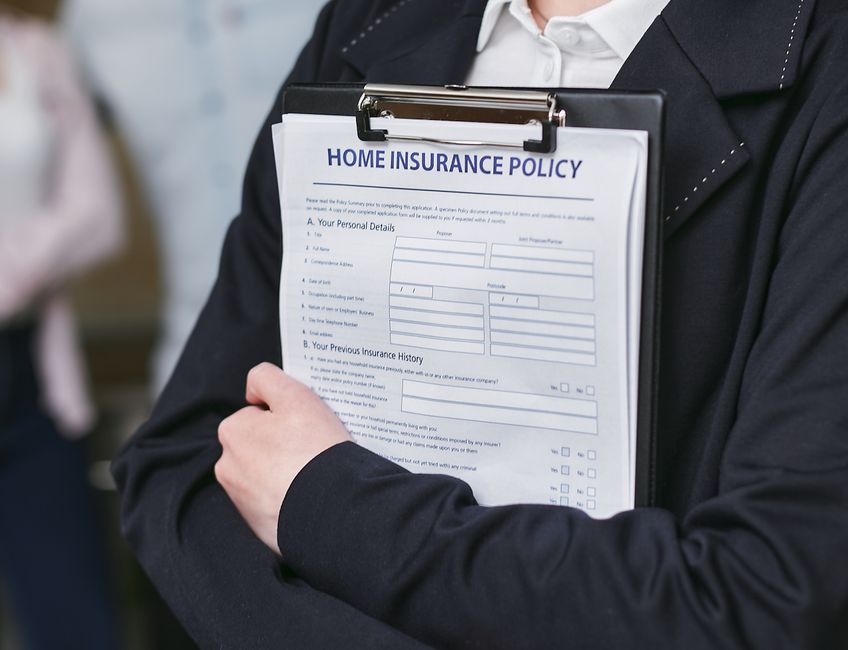
Moving insurance and valuation coverage sound like the same thing, but they are not, and mixing them up is one of the most expensive mistakes people make on moving day. Valuation coverage is a built-in liability option every moving company must offer, while moving insurance is a separate policy you buy from a third-party insurer. Knowing the difference before you sign a contract determines whether a broken heirloom or a damaged sofa actually gets paid for.
If you are researching how to protect your belongings during a move in Buffalo, here is what each option covers, what it costs, and how to decide which one (or both) you actually need.
What Is the Difference Between Moving Insurance and Valuation Coverage?
Valuation coverage is a liability level set by the moving company and regulated by federal law for interstate moves; it is not technically insurance. Moving insurance is a true insurance product, sold by a licensed third-party carrier, that can cover losses valuation does not touch, like accidental damage from natural disasters or full replacement value beyond what a mover offers.
The distinction matters because valuation is included with every move whether you ask for it or not, at the most basic level. Moving insurance is optional, costs extra, and needs to be arranged separately, usually before moving day. Movers can sell you valuation upgrades, but they generally cannot sell you insurance directly; that has to come from a licensed agent or an existing policy like homeowners or renters insurance with a moving rider.
How Does Released Value Protection Work?
Released value protection is the free, basic coverage included with most moves, and it pays out based on weight, not actual item value. That means a shattered 50-inch TV and a shattered lamp could be reimbursed at the same rate if they weigh the same, which is rarely a fair outcome.
For interstate moves, released value protection is capped at a set rate per pound per article (commonly around 60 cents), regardless of what the item cost. On a local move within New York, the cap works differently but the principle is the same: you get pennies on the dollar for anything damaged or lost. This coverage is automatically included at no charge, which is exactly why so many people assume they are protected and then are disappointed when a claim comes back for a few dollars.
Released value protection makes sense only if you are moving items that are already low in value or fully depreciated. For anything you would actually miss, it is not real protection, it is a formality.
Is Full Value Protection Worth the Extra Cost?
Full value protection is worth it for most households because it requires the mover to repair, replace, or reimburse an item at its current market value if it is damaged or lost, rather than paying by weight. It costs more than released value protection, but the gap between what you pay and what you would lose in a released-value claim is usually significant.
The cost of full value protection typically scales with the total declared value of your shipment, so a studio apartment move will cost far less to insure than a four-bedroom house. Ask your moving company how they calculate the premium and whether there is a deductible option, since a higher deductible can lower the cost while still protecting your highest-value items.
One detail people miss: full value protection still allows the mover to choose repair over replacement, and it may exclude items you packed yourself unless the box shows obvious external damage. Boxes you packed yourself are typically covered only for concealed damage if there is visible crushing or tampering, which is one more reason many people choose professional packing services for higher-value items.
When Should You Buy Separate Moving Insurance?
You should consider separate moving insurance when your belongings exceed what valuation coverage realistically pays out, when you are moving high-value specialty items, or when you want protection against risks valuation does not cover at all, like a move disrupted by a natural disaster. Valuation only addresses the mover's liability; it does not function as all-risk insurance.
Common situations where separate coverage makes sense include:
- Moving fine art, antiques, or collectibles with values hard to document by weight
- Moving items your homeowners or renters policy specifically excludes during transit
- Long-distance or interstate moves where goods are in transit for multiple days
- High-value electronics, musical instruments, or other specialty items
If your move includes items like these, it is worth reviewing coverage options with your moving company's specialty moving services team before the move date, since specialty items often need both careful handling and a documented value in advance.
How Do You File a Damage Claim With a Moving Company?
Filing a claim starts with documenting the damage in writing and photos before anything is thrown away or repaired, then submitting a written claim to the mover within the timeframe stated in your contract, which is often nine months for interstate moves. Waiting too long or disposing of the damaged item before the mover inspects it can void your claim entirely.
Practical steps that make a claim go smoothly:
- Note any visible damage on the bill of lading before the crew leaves, not after
- Photograph damaged items and packaging from multiple angles
- Keep the original box and packing materials if a concealed-damage claim is possible
- Submit your claim in writing with your inventory list and photos attached
- Follow up in writing, not just by phone, so there is a paper trail
A mover with a clear, published claims process is usually a sign they stand behind their valuation and insurance options rather than treating them as a formality. That is worth asking about directly when you request quotes.
Which Coverage Should You Choose for Your Buffalo Move?
For most local moves with an average household's worth of furniture and boxes, full value protection through your mover is enough, especially when paired with careful packing. For long-distance moves, high-value items, or anything irreplaceable, adding third-party moving insurance closes the gaps that valuation leaves open.
The safest approach is to inventory your belongings before your move, decide which items genuinely need extra protection, and ask your mover to walk through the specific valuation options available for your long-distance move or local relocation. A reputable Buffalo moving company should be able to explain these options clearly instead of burying them in fine print.
If you are still weighing your options or want a written breakdown of coverage for your specific move, get in touch with Alpaca Movers before booking so there are no surprises on moving day.
Frequently Asked Questions
Does homeowners insurance cover items damaged during a move?
Sometimes, but coverage varies widely by policy and often excludes items in transit or being handled by a moving company. Check with your insurance provider before relying on a homeowners or renters policy to cover a move, and ask specifically whether in-transit damage is included.
Is released value protection free with every move?
Yes, released value protection is included at no extra charge with most moving company contracts, since federal regulations require movers to offer it as a baseline option. However, it pays out based on weight rather than actual item value, so it rarely covers the true cost of a damaged item.
Can I buy moving insurance directly from my moving company?
Movers can offer valuation coverage upgrades, but true third-party moving insurance typically has to be purchased separately from a licensed insurance agent or broker. Some moving companies can refer you to a partner insurer, but the policy itself is not sold as part of the moving contract.
What items are usually excluded from moving valuation coverage?
Cash, jewelry, important documents, and items of extraordinary value are commonly excluded or require separate written declaration before the move. Items packed by the owner instead of the moving crew may also have limited coverage unless there is visible external damage to the box.
How much does full value protection typically cost?
Cost usually scales with the total declared value of your shipment and can include a deductible option to lower the premium. Ask your mover for a written quote on full value protection alongside your standard moving estimate so you can compare the actual dollar difference.

Alpaca Movers has you covered!


Open 24 hrs